IRS Announces Withdrawal Process for Employee Retention Credit Claims - Special Initiative Aimed at Helping Businesses Concerned About an Ineligible Claim Amid Aggressive Marketing, Scams
As part of a larger effort to protect small businesses and organizations from scams, the Internal Revenue Service announced the details of a special withdrawal process to help those who filed an Employee Retention Credit (ERC) claim and are concerned about its accuracy.
This new withdrawal option allows certain employers that filed an ERC claim but have not yet received a refund to withdraw their submission and avoid future repayment, interest, and penalties. Employers that submitted an ERC claim that’s still being processed can withdraw their claim and avoid the possibility of getting a refund for which they are ineligible.
The IRS created the withdrawal option to help small business owners and others who were pressured or misled by ERC marketers or promoters into filing ineligible claims. Claims that are withdrawn will be treated as if they were never filed. The IRS will not impose penalties or interest.
Those who willfully filed a fraudulent claim, or those who assisted or conspired in such conduct, should be aware that withdrawing a fraudulent claim will not exempt them from potential criminal investigation and prosecution.
When properly claimed, the ERC – also referred to as the Employee Retention Tax Credit or ERTC – is a refundable tax credit designed for businesses that continued paying employees during the COVID-19 pandemic while their business operations were fully or partially suspended due to a government order, or they had a significant decline in gross receipts during the eligibility periods. The credit is not available to individuals.
The ERC is a complex credit with precise requirements to help businesses during the pandemic, and since mid-September, the IRS has received approximately 3.6 million claims for the credit over the course of the program.
In July, the IRS said it was shifting its focus to review ERC claims for compliance concerns, including intensifying audit work and criminal investigations on promoters and businesses filing dubious claims. The IRS has hundreds of criminal cases being worked, and thousands of ERC claims have been referred for audit.
The new withdrawal process follows the Sept. 14 announcement of an immediate moratorium on processing new ERC claims. The moratorium, which will last until at least the end of this year, follows a flood of ineligible ERC claims. Payouts for claims submitted before Sept. 14 will continue during the moratorium period but at a slower pace due to more detailed compliance reviews. With stricter compliance reviews in place, existing ERC claims will go from a standard processing goal of 90 days to 180 days – and much longer if the claim faces further review or audit. The IRS may also seek additional documentation from the taxpayer to ensure the claim is legitimate.
Enhanced compliance reviews of existing claims submitted before the moratorium is critical to protect against fraud but also to protect businesses and organizations from facing penalties or interest payments stemming from bad claims pushed by promoters.
The IRS continues to warn taxpayers to use extreme caution before applying for the ERC as aggressive maneuvers continue by marketers and scammers.
The IRS is also working on guidance to help employers that were misled into claiming the ERC and have already received the payment. More details will be available this fall.
Who can ask to withdraw an ERC claim?
Employers can use the ERC claim withdrawal process if of all the following apply:
- They made the claim on an adjusted employment return (Forms 941-X, 943-X, 944-X, CT-1X).
- They filed the adjusted return only to claim the ERC, and they made no other adjustments.
- They want to withdraw the entire amount of their ERC claim.
- The IRS has not paid their claim, or the IRS has paid the claim, but they haven’t cashed or deposited the refund check.
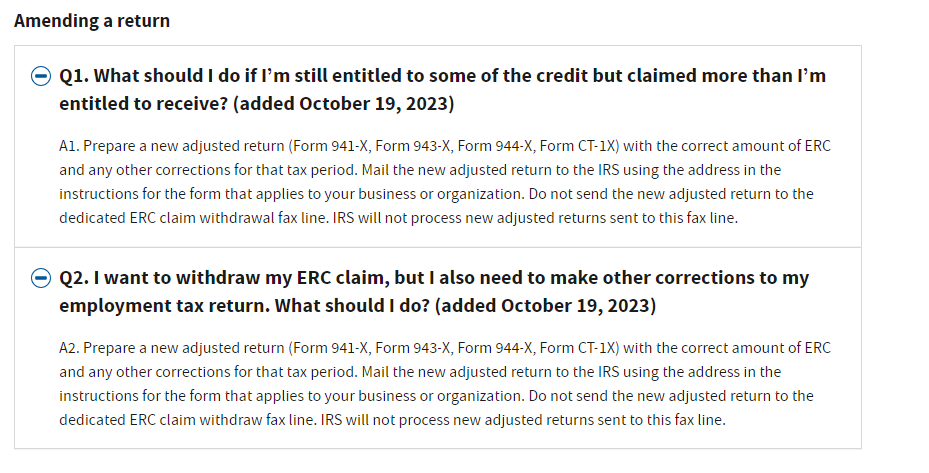
Taxpayers who are not eligible to use the withdrawal process can reduce or eliminate their ERC claim by filing an amended return. For details, see the Correcting an ERC claim – Amending a return section of the frequently asked questions about the ERC.
How to withdraw an ERC claim
To take advantage of the claim withdrawal procedure, taxpayers should carefully follow the special instructions at IRS.gov/withdrawmyERC, summarized below.
- Taxpayers whose professional payroll company filed their ERC claim should consult with the payroll company. The payroll company may need to submit the withdrawal request for the taxpayer, depending on whether the taxpayer’s ERC claim was filed individually or batched with others.
- Taxpayers who filed their ERC claims themselves, haven’t received, cashed, or deposited a refund check and have not been notified their claim is under audit should fax withdrawal requests to the IRS. The IRS has set up a special fax line to receive withdrawal requests. This enables the agency to stop processing before the refund is approved. Taxpayers who are unable to fax their withdrawal can mail their request, but this will take longer for the IRS to receive.
- Employers who have been notified they are under audit can send the withdrawal request to the assigned examiner or respond to the audit notice if no examiner has been assigned.
Those who received a refund check, but haven’t cashed or deposited it, can still withdraw their claim. They should mail the voided check with their withdrawal request using the instructions at IRS.gov/withdrawmyERC.
Section A: The has not received a refund and has not been notified the claim is under audit.
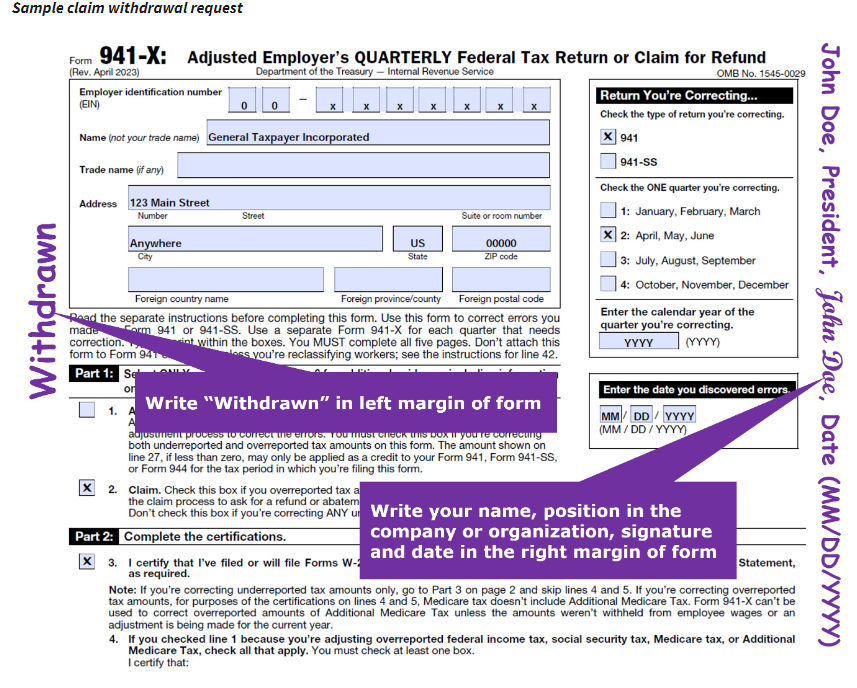
If you filed an adjusted return (Form 941-X, 943-X, 944-X, CT-1X) to claim the ERC and you would like to withdraw your entire claim, use the process below. If you filed adjusted returns for more than one tax period, you must follow the steps below for each tax period for which you are requesting a withdrawal.
To request a withdrawal, follow these steps:
- Make a copy of the adjusted return with the claim you wish to withdraw.
- In the left margin of the first page, write “Withdrawn.”
- In the right margin of the first page:
- Have an authorized person sign and date it.
- Write their name and title next to their signature.
- Fax the signed copy of your return using your computer or mobile device to the IRS’s ERC claim withdrawal fax line at 855-738-7609. This is your withdrawal request. Keep your copy with your tax records.
If you cannot fax your withdrawal request, you can mail it to the address in the instructions for the adjusted return that applies to your business or organization. Before doing so you should make a copy of the signed and dated first page to keep for your records. It will take longer for the IRS to receive your request if you mail it. Track your package to confirm delivery.
Upcoming webinar and other resources for help
Tax professionals and others can register for a Nov. 2 IRS webinar, Employee Retention Credit: Latest information on the moratorium and options for withdrawing or correcting previously filed claims. Those who cannot attend can view a recording later.
The IRS unveiled a new question and answer checklist last month to help taxpayers understand if they’re eligible for the credit. Since then, the IRS evolved the checklist into an interactive IRS.gov feature to help employers – and the tax professionals working with them – check potential ERC eligibility.
New approach from scammers
Marketers and scammers have already revised their ERC pitches following the Sept. 14 moratorium announcement. Some are pushing employers who submit an ERC claim into agreeing to costly up-front loans in anticipation of a refund.